
The electrification of China’s logistics sector has moved with remarkable speed. JD.com’s delivery fleet — which the company publicly committed to full electrification with specific vehicle count targets — has become one of the world’s largest commercial EV fleets. SF Express, China’s premium express logistics operator, has similarly electrified significant proportions of its last-mile delivery and sorting centre shuttle operations. Cainiao (菜鸟), Meituan (美团), and Ele.me (饿了么) have deployed electric delivery vehicles at scales that dwarf most national EV fleets.
The operational challenge that has emerged from this rapid electrification is not primarily a vehicle or hardware challenge — China’s commercial EV market has produced capable last-mile delivery vehicles, sortation shuttles, and medium-duty distribution trucks that meet most operational specifications. The challenge that logistics companies at every scale from JD.com’s 100,000+ vehicle fleet down to a regional express operator’s 200-vehicle fleet consistently identify as their most significant operational constraint is charging management: ensuring that the right vehicle has the right charge level at the right time, at the lowest possible electricity cost, without exceeding grid capacity constraints or creating depot congestion that delays departure schedules.
This guide on fleet charging management 2026 software for Chinese logistics companies JD.com SF Express provides the complete analysis of the Chinese fleet charging management software landscape — what these platforms actually do, how the major systems compare for different fleet scales and operational profiles, the specific features that differentiate adequate from excellent fleet charging management, and the buying decision framework for logistics companies at different scales evaluating their options.
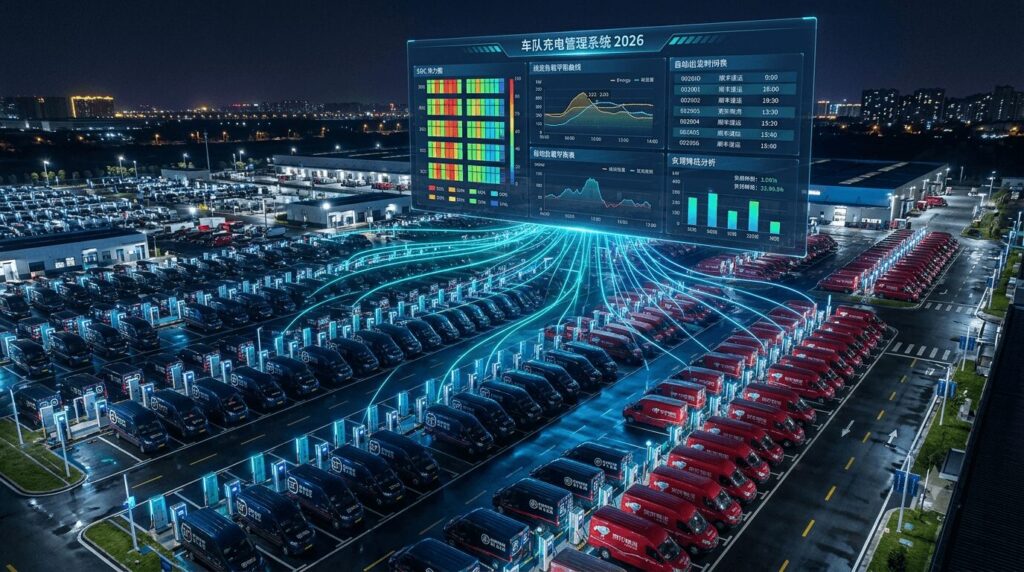
What Fleet Charging Management Software Actually Does
The Core Problem That Fleet Charging Management Solves
The unmanaged fleet charging scenario:
Without fleet charging management software, Chinese logistics companies with depot-based EV fleets face a specific operational pattern that has been extensively documented across early-adopter logistics operators:
Every vehicle returns to the depot at roughly similar times (end of delivery shift). Every driver plugs in to the nearest available charging point. All vehicles begin charging simultaneously. The aggregate current draw significantly exceeds the depot’s grid connection capacity. The distribution board trips, or demand charges spike dramatically, or both.
Simultaneously, vehicles that arrive with adequate battery for the next shift but well below maximum SOC receive a full charge to maximum at peak grid cost — unnecessary electricity cost that optimised scheduling would avoid. Vehicles that genuinely need priority charging based on next-shift distance requirements receive the same scheduling priority as vehicles that could comfortably wait until late-night valley rates.
What fleet charging management software specifically resolves:
A properly configured fleet charging management system transforms this unmanaged scenario into a coordinated, optimised, automatically-managed charging operation by:
Function 1: SOC-informed priority scheduling
The system queries each vehicle’s current battery SOC (through telematics integration or manual driver input) and cross-references against the next shift’s planned route distance and departure time, automatically assigning charging priority based on genuine energy need rather than arrival order.
Function 2: Load management across the depot’s total grid capacity
The system monitors the depot’s total current draw in real-time and dynamically allocates available charging capacity across all connected vehicles, ensuring the aggregate draw stays within the grid connection capacity while maximising utilisation of available capacity. This directly addresses the panel-trip scenario while also minimising demand charges that commercial electricity tariffs impose based on peak demand.
Function 3: TOU optimisation at fleet scale
The system schedules charging sessions across the fleet to concentrate consumption in valley rate periods where possible — the same financial principle covered in our residential TOU guides, but applied at fleet scale where the financial impact is proportionally larger. A 200-vehicle fleet saving ¥1,200/year per vehicle through TOU optimisation generates ¥240,000/year fleet-level savings.
Function 4: Predictive availability assurance
The system forecasts whether each vehicle will reach its required departure SOC at the scheduled departure time given current charging status and planned schedule, flagging vehicles at risk of insufficient charge for intervention before the departure window.
Function 5: Operational reporting for compliance and cost accounting
The system generates the session logs, energy consumption records, and cost allocation reports required for fleet operator internal accounting, government fleet mandate compliance documentation (covered in our government fleet charging guide), and electricity cost recovery from owner-operators in franchise delivery model operations.
The Fleet Charging Management Software Landscape in China
The Major Platforms Serving Chinese Logistics Fleets
Platform Category 1: Major Charging Network Operators’ Fleet Modules
Both TELD and StarCharge — whose commercial charging equipment is covered in our gas station conversion guide — offer fleet management software modules designed for operators using their charging hardware. These are the most widely deployed fleet management systems among Chinese logistics operators by installed base.
TELD e+ Fleet Management (特来电e+车队管理):
TELD’s fleet management platform, developed from their experience managing China’s largest commercially-operated public charging network, brings genuine operational scale experience to fleet deployment.
Key capabilities:
- Multi-depot management across unlimited locations within a single platform instance
- Real-time SOC monitoring for all connected vehicles (requiring telematics integration or TELD-compatible charger communication)
- Demand response participation management at fleet scale, with automated curtailment scheduling during demand response events and automated income distribution
- Cost allocation reporting to vehicle/driver/route level for internal chargebacking
- OCPP 2.0 backend for full standards compliance
- API integration with major logistics TMS (Transport Management Systems) including JD Logistics’ internal systems and third-party TMS platforms used by regional operators
Pricing model: Hardware-bundled (TELD commercial charger purchase includes platform access) plus per-vehicle-per-month SaaS fee for vehicles on non-TELD chargers: approximately ¥30-¥80/vehicle/month
Best for: Operators who have selected or are considering TELD commercial charging hardware, operators with multi-depot operations, operators with complex demand response participation requirements
StarCharge Fleet Solution (星星充电车队方案):
StarCharge’s fleet management offering, similar to TELD’s in its hardware-bundled model, offers specific strengths in the modular power-sharing architecture covered in our gas station conversion guide — where StarCharge’s hardware design allows dynamic power reallocation between charging points, their software platform’s utilisation of this capability provides more flexible load management than fixed-power charging points with software-only load management.
Key capabilities:
- Modular power sharing optimisation (specific to StarCharge’s modular hardware)
- Fleet cost accounting with vehicle-level cost tracking
- Shift-based scheduling aligned with logistics operation patterns
- WeChat Work integration for driver notification and charging status visibility
- OCPP 2.0 compliance
Pricing model: Hardware-bundled, per-vehicle SaaS approximately ¥25-¥60/vehicle/month
Best for: Operators using StarCharge’s modular commercial charging hardware, operators who value tight WeChat Work integration for driver communication
Platform Category 2: Dedicated Fleet EV Management SaaS Platforms
A category of software-specialist companies has emerged specifically targeting fleet EV management as a distinct SaaS category, hardware-agnostic (compatible with any OCPP 2.0 charging equipment) and integrating with vehicle telematics from multiple OEM sources.
Charge Now Fleet (充现在车队版):
Charge Now’s fleet management platform represents the most developed hardware-agnostic fleet EV management SaaS in China’s market, with integration across multiple charging hardware brands and vehicle telematics systems.
Key capabilities:
- Hardware-agnostic OCPP 2.0 backend (compatible with TELD, StarCharge, ABB, Huawei, and other commercial chargers)
- Multi-brand vehicle telematics integration (BYD DiLink, NIO Connect, Xpeng XNGP data, and generic OBD telematics)
- AI-powered charging schedule optimisation with reinforcement learning that improves schedule quality based on actual vehicle performance history
- Route integration with major Chinese logistics TMS platforms
- Multi-tenant deployment for franchise logistics networks (relevant for JD.com’s franchisee-operated last-mile stations)
- Driver app (iOS and Android) with charging status, departure readiness, and issue reporting
- Grid demand forecast integration (using meteorological and historical load data to predict grid pricing windows more accurately than fixed TOU schedule assumptions)
Pricing model: Per-vehicle-per-month SaaS, approximately ¥45-¥120/vehicle/month depending on feature tier; no hardware bundling requirement
Best for: Mixed-hardware fleets, operators wanting hardware procurement flexibility, franchise logistics networks with distributed depot management
Qingneng Fleet (青能车队管理):
A newer entrant with strong investment backing that has developed fleet EV management specifically targeting medium-sized Chinese logistics operators (50-500 vehicles) who are too large for basic charger-bundled management but lack the resources for enterprise-grade platforms.
Key capabilities:
- Optimised for medium-fleet scale operational complexity
- Simplified onboarding (3-day deployment timeline versus typical 2-4 week enterprise deployment)
- Fixed-price deployment model reducing TCO uncertainty
- WeChat mini-program driver interface eliminating separate app download requirement
- Basic TMS integration for JD.com and SF Express franchisee operators through pre-built connectors
Pricing model: Fixed monthly fee per depot rather than per vehicle, approximately ¥3,000-¥8,000/depot/month; simpler pricing structure for operators finding per-vehicle SaaS complex to budget
Best for: Medium fleet operators (50-500 vehicles), JD/SF franchisee operators wanting standardised TMS integration, operators prioritising rapid deployment over maximum feature depth
Platform Category 3: OEM-Integrated Fleet Management
Major Chinese commercial EV manufacturers have developed fleet management software that integrates directly with their vehicles’ telematics:
BYD 智慧车队 (BYD Smart Fleet):
BYD’s fleet management platform, integrated with BYD commercial vehicle telematics, provides the most native integration for fleets operating primarily BYD vehicles — battery cell-level telemetry, Blade Battery health monitoring, and BYD-specific charging optimisation that leverages detailed battery state information beyond standard SOC.
Key capabilities:
- Cell-level Blade Battery monitoring for degradation prediction
- Native BYD vehicle telematics (no third-party telematics hardware required)
- Integration with BYD’s commercial charging equipment
- Predictive maintenance alerts based on battery cell behaviour patterns
Limitation: Single-brand dependency — optimal for BYD-exclusive fleets, significantly reduced value for mixed-brand fleets
Pricing model: Bundled with BYD commercial vehicle purchase (fleet pricing negotiated with BYD commercial sales); separate software-only licensing available for fleets acquired through used vehicle markets
Best for: BYD-exclusive logistics fleets, operators placing significant value on cell-level battery health monitoring
The Feature Deep Dive — What Separates Good From Excellent
Feature 1: Real-Time SOC Integration Quality
Why this is the most critical feature for logistics operations:
Fleet charging management software is only as useful as the SOC data it operates on. Platforms that rely on driver-reported SOC (manual entry in a driver app) introduce human error and intentional misrepresentation (drivers who overstate SOC to avoid being assigned early charging may understate to get priority). Platforms with direct telematics integration bypass this entirely.
The telematics integration spectrum:
Native OEM integration (BYD Smart Fleet for BYD vehicles, NIO for NIO vehicles): highest data quality, real-time cell-level data, but single-brand
OCPP-based SOC reporting through charger communication: accurate when vehicle is connected but provides no data between connections
Third-party telematics hardware (OBD dongle or purpose-installed telematics unit): hardware cost and installation requirement but provides continuous SOC visibility across any vehicle brand
What to specify: For mixed-brand fleets, third-party telematics hardware with fleet management software integration provides the most consistent SOC data quality across the fleet regardless of vehicle brand. For single-brand fleets, native OEM integration is clearly superior and eliminates additional hardware cost.
Feature 2: Demand Charge Management
The commercial electricity cost element that residential guides don’t address:
As covered in our residential TOU guides, residential electricity pricing involves a straightforward time-of-use structure. Commercial electricity pricing for large consumers includes an additional component that fundamentally changes the financial optimisation problem: demand charges (需量费/容量费).
How demand charges work:
Commercial electricity accounts with transformer capacity above approximately 100 kVA are billed not only for energy consumed (kWh) but also for peak demand (kW or kVA) within each billing period. Demand charges in China typically range from ¥20-¥60/kW of peak demand per month, measured as the highest 15-minute or 30-minute average power demand during the billing period.
The financial scale at logistics fleet level:
A 200-vehicle fleet where unmanaged charging creates a 1,000 kW peak demand incurs:
1,000 kW × ¥40/kW/month = ¥40,000/month in demand charges = ¥480,000/year
The same fleet with demand management limiting peak to 600 kW:
600 kW × ¥40/kW/month = ¥24,000/month = ¥288,000/year
Demand charge saving from fleet charging management: ¥192,000/year — often the single largest financial benefit from fleet charging management software, exceeding even TOU optimisation savings at fleet scale.
What to specify: Demand charge management that targets not just TOU optimisation but specifically peak demand reduction, with configurable peak demand limits and automatic current reduction when the rolling 15-minute demand approaches the limit. This feature is non-negotiable for any fleet exceeding 50 vehicles at a single depot.
Feature 3: Multi-Depot Coordination
The specific complexity that separates regional logistics operations from single-depot operators:
JD.com’s logistics network, SF Express’s hub-and-spoke system, and any regional logistics operator with multiple warehouse or distribution centres across Chinese cities require fleet charging management that coordinates charging across multiple physical locations simultaneously.
The multi-depot coordination problem:
A regional logistics operator with 6 depots across a province has vehicles that may charge at multiple depots within a single operational period — a vehicle based at Depot A that makes a delivery run to Depot C and charges there before returning creates a charging record at Depot C that must be correctly attributed to the vehicle’s home depot for cost accounting, and the charge at Depot C must be managed within Depot C’s capacity constraints alongside Depot C’s own home fleet vehicles.
What to specify: True multi-depot management with vehicle-level cost attribution across depots, not simply separate single-depot management instances that happen to share a reporting dashboard. The distinction is whether a vehicle’s charging history at any depot is accessible to fleet management regardless of which depot it charged at — critical for total fleet cost visibility.
Feature 4: Franchise and Multi-Tenant Architecture
The specifically Chinese logistics network structure that requires this:
JD.com and SF Express both operate through franchise networks alongside their directly-operated fleets. Franchise operators — independent businesses that operate delivery vehicles under JD or SF brand agreements — have their own EV fleets, their own depot facilities, and their own electricity accounts, but their charging costs and fleet performance may be subject to reporting requirements to the franchisor.
What franchise-appropriate fleet charging management requires:
Multi-tenant architecture where the franchisor (JD, SF) has visibility into charging performance metrics and compliance reporting across all franchisee operations, while franchisee operators maintain control over their own operational parameters and cannot see other franchisees’ detailed data.
Standardised reporting format that allows the franchisor to aggregate fleet electrification performance data across the entire franchise network for government compliance reporting (relevant to government fleet mandate requirements covered in our government fleet guide) and corporate sustainability reporting.
What to specify: Explicit multi-tenant architecture with role-based access control distinguishing franchisor visibility from franchisee operational control. Verify this architecture capability with specific reference to the use case rather than accepting generic “enterprise access control” claims.
Feature 5: Integration With Chinese Logistics TMS
The operational integration that determines adoption success:
Fleet charging management software that operates as a separate system requiring separate login, separate data entry, and separate workflow from the TMS (Transport Management System) that dispatchers use for route planning and vehicle assignment will have low adoption — dispatchers will not use a separate system when their primary operational tool doesn’t surface charging status.
The key integrations for Chinese logistics:
Integration with JD Logistics’ internal TMS: relevant for JD franchise operators
Integration with SF Express’s operational systems: relevant for SF franchise operators
Integration with Cainiao’s warehouse management and dispatch systems: relevant for Alibaba logistics ecosystem participants
Integration with general-purpose Chinese TMS platforms (运联通, 56freight, 货拉拉企业版): relevant for regional operators using third-party TMS
What to specify: Verify specific integration with your actual TMS platform — not generic “API integration available” but specific confirmation that the integration covers the specific data flows your dispatchers need (vehicle availability by SOC, charging status in vehicle selection, departure readiness alerts in dispatch workflow).
The Scale-Appropriate Platform Selection Framework
For Small Fleets (20-100 Vehicles)
The specific small fleet challenge:
Fleets below approximately 100 vehicles often cannot justify the monthly SaaS cost of enterprise-grade fleet charging management platforms, particularly when the fleet’s operational complexity (typically single depot, single shift pattern, limited TMS integration requirement) doesn’t utilise most enterprise-grade features.
The appropriate platform tier:
Charger-bundled platform from the commercial charger supplier (TELD e+ or StarCharge fleet module) provides adequate functionality for small fleets at the lowest incremental cost above the charger equipment purchase. The platform’s capabilities — basic load management, TOU scheduling, session logging, simple reporting — are appropriate for the operational complexity of small single-depot fleets.
The specific small fleet feature to prioritise: Driver notification through WeChat (universal in China, no additional app required) for charging status and departure readiness alerts — the single highest-adoption communication channel for driver-facing fleet management features in the Chinese market.
Estimated platform cost: ¥0-¥25/vehicle/month (effectively bundled with charger hardware)
For Medium Fleets (100-500 Vehicles)
The specific medium fleet challenge:
Medium fleets have sufficient scale to justify standalone fleet charging management software but often insufficient internal IT resources to manage complex enterprise platform deployments. They need meaningful feature depth — particularly demand charge management and multi-depot support — without enterprise deployment complexity.
The appropriate platform tier:
Dedicated mid-market SaaS (Qingneng Fleet or equivalent mid-market platform) with fixed-per-depot pricing that simplifies budget planning, rapid deployment timelines, and pre-built connectors for the most common Chinese logistics TMS platforms.
The specific medium fleet feature to prioritise: Demand charge management — at 100-500 vehicles, demand charges represent the largest single avoidable electricity cost, and the platform’s demand charge management sophistication directly determines the most significant financial return from the software investment.
Estimated platform cost: ¥3,000-¥8,000/depot/month
For Large Fleets (500+ Vehicles)
The specific large fleet challenge:
At 500+ vehicles across multiple depots, fleet charging management software is a significant operational system requiring enterprise-grade reliability, API integration with existing enterprise systems (ERP, TMS, HR for driver management), multi-tenant architecture for franchise networks, and sophisticated optimisation that simple rule-based systems cannot deliver.
The appropriate platform tier:
Enterprise-grade platform with AI optimisation (Charge Now Fleet or purpose-built enterprise deployment) with full API integration capability, genuine multi-tenant architecture, and the scaling capacity to handle fleet growth without platform migration.
The specific large fleet feature to prioritise: AI-powered optimisation quality — at 500+ vehicles, the difference between rule-based charging schedule optimisation and reinforcement learning-based optimisation that continuously improves based on actual vehicle performance history translates to measurable cost differences of ¥500-¥2,000/vehicle/year, justifying the higher platform cost.
Estimated platform cost: ¥60-¥120/vehicle/month for enterprise tier
The Financial Impact Summary
The Quantified Case for Fleet Charging Management Investment
Reference: 200-vehicle logistics fleet, single depot, mixed shift pattern, Wuhan location
Without fleet charging management:
Peak demand: 1,200 kW (unmanaged simultaneous charging)
Annual demand charges: 1,200 × ¥35 × 12 = ¥504,000/year
TOU optimisation: 30% of charging during valley (unmanaged pattern)
Annual electricity cost (non-demand): ¥720,000/year
With fleet charging management:
Peak demand reduced to: 600 kW (managed load distribution)
Annual demand charges: 600 × ¥35 × 12 = ¥252,000/year
TOU optimisation: 75% of charging during valley (managed scheduling)
Annual electricity cost (non-demand): ¥580,000/year
Annual savings:
Demand charge reduction: ¥252,000/year
TOU optimisation improvement: ¥140,000/year
Total annual saving: ¥392,000/year
Platform cost (mid-market tier):
¥5,000/month × 12 = ¥60,000/year
Net annual benefit: ¥332,000/year
ROI: 553% on platform cost
Payback on platform implementation cost (typically ¥30,000-¥80,000 for deployment): under 3 months
The JD.com and SF Express Specific Context
How China’s Largest Logistics Operators Are Actually Managing Fleet Charging
JD Logistics (京东物流):
JD Logistics’ scale — one of the world’s largest commercial EV fleets — requires fleet charging management at a level of sophistication that has driven JD to develop significant internal capability alongside external platform partnerships. Key elements of JD’s fleet charging management approach that smaller operators can learn from:
Route integration as the foundation: JD’s fleet charging management is integrated at the route planning level — charging requirements are calculated from planned route distances before vehicle dispatch, not after return. This allows proactive charging priority assignment rather than reactive priority based on returned SOC.
Multi-tier charging infrastructure: JD operates a combination of high-power DC fast charging at major sorting hubs (enabling rapid charge between shift segments for high-utilisation vehicles) and lower-power AC charging at residential delivery station locations (overnight charging for last-mile delivery vehicles that return to local stations).
Electricity procurement sophistication: At JD Logistics’ scale, the company has developed direct electricity procurement relationships with grid companies, including demand response programme participation across its depot portfolio that generates meaningful income from grid services — the commercial-scale version of the residential demand response income covered in our connectivity guide.
SF Express (顺丰速运):
SF Express’s premium positioning in Chinese logistics (higher-value parcels, time-sensitive delivery) creates specific fleet charging requirements that emphasise departure reliability over cost optimisation — an SF delivery vehicle failing to charge adequately for a guaranteed morning delivery commitment creates customer experience and brand damage that outweighs the electricity cost saving from aggressive TOU optimisation.
Key elements of SF Express’s fleet charging management approach:
Departure assurance as the primary metric: SF’s fleet charging management prioritises “departure SOC attainment rate” — the percentage of scheduled departures where the vehicle achieves its required minimum SOC before the departure window — as the primary KPI, above electricity cost optimisation metrics.
Premium charging infrastructure investment: SF invests in higher power-level charging at key depots specifically to ensure departure SOC attainment rate is maintained even during periods of delayed vehicle returns or unexpectedly high consumption during preceding shifts.
Driver incentive integration: SF’s fleet charging management software includes driver performance metrics that connect driver charging behaviour (proper connection at return, accurate manual SOC confirmation where telematics is incomplete) to driver performance scoring in SF’s incentive system.
The Implementation Considerations
What Fleet Operators Consistently Underestimate
Underestimate 1: Driver behaviour change management
Fleet charging management software changes driver behaviour — specifically, it removes driver discretion about when and how their vehicle charges. Drivers who previously plugged in and walked away now encounter a system that may not immediately begin charging because their vehicle is at lower priority. Without adequate change management, driver resistance (deliberate misreporting of SOC, unplugging vehicles to “help” lower-SOC vehicles) can undermine system optimisation.
The mitigation: Driver communication before deployment explaining the system’s logic and the fleet-wide benefit, combined with driver app visibility into their specific vehicle’s charging queue position and estimated departure SOC — transparency that converts driver relationship from opponent to participant in the optimisation.
Underestimate 2: Telematics deployment timeline and cost
For mixed-brand fleets where native telematics integration is unavailable, deploying third-party telematics hardware across the fleet — procurement, installation at a licensed workshop, activation, system configuration — typically takes 6-10 weeks and costs ¥800-¥2,000 per vehicle. This is often the longest single element in fleet charging management deployment timelines and one of the most frequently underestimated cost components.
Underestimate 3: Grid upgrade lead times
Fleet charging management software optimises the use of available grid capacity — it doesn’t create additional capacity. For depots whose current grid connection is inadequate for the required total charging load even with optimised scheduling, grid upgrade is a prerequisite rather than a subsequent enhancement. As covered in our SGCC guide’s commercial context, medium-voltage grid upgrades for commercial depots take 60-120 working days — the longest approval process in the deployment pathway.
Internal Links — Further Reading on Clean Energy Bazaar
The fleet charging management 2026 software for Chinese logistics companies JD.com SF Express guide connects to the commercial charging, government fleet, and technology platform guidance throughout this content cluster.
For the government fleet charging guide that covers the institutional procurement and compliance reporting requirements that fleet charging management software must support, our public sector opportunity guide to China’s 25 percent government fleet charging mandate guide covers every compliance consideration. For the commercial DC fast charger guide covering the hardware that fleet charging management software manages, our how to choose commercial DC fast chargers for your Chinese gas station conversion guide covers every commercial hardware specification. For the great shakeout guide contextualising fleet charging software brand selection within the broader market consolidation, our great shakeout why 80 percent of Chinese EV charger manufacturers face elimination in 2026 guide covers the complete industry landscape. For the load balancing guide that covers the residential-scale version of the demand management principles applied at fleet scale throughout this guide, our load balancing EV chargers 2026 avoid tripping breakers in old Chinese apartment blocks guide covers the fundamental principles. For the connectivity guide covering OCPP 2.0 standards that fleet charging management platforms depend on, our best smart connectivity WiFi 5G digital yuan payments in Chinese smart chargers guide covers every connectivity specification. And for the rural charging guide covering the rural depot context where smaller logistics operator fleet management requirements differ from major urban operations, our rural charging boom 2026 how to start a charging business in China’s 59 new pilot counties guide covers the rural operational context.
Final Thoughts
The fleet charging management 2026 software for Chinese logistics companies JD.com SF Express landscape has matured significantly from the early improvised approaches that characterised the first wave of Chinese logistics fleet electrification. The platforms available in 2026 — from TELD and StarCharge’s hardware-bundled modules through dedicated mid-market SaaS to enterprise AI-optimised platforms — provide genuine operational capability across the full range of Chinese logistics fleet scales and complexity profiles.
The financial case for fleet charging management software is not marginal — the demand charge management benefit alone for a 200-vehicle fleet generates ¥252,000/year in savings against a platform cost of ¥60,000/year, producing 420% ROI before accounting for TOU optimisation, departure reliability improvements, and operational reporting efficiency. This is not a technology investment that requires optimistic assumptions to justify; it is a straightforward operational efficiency investment with compelling and rapidly-realised returns.
The platform selection guidance this guide has provided — charger-bundled platforms for small fleets where operational complexity doesn’t justify additional software investment, mid-market dedicated SaaS for medium fleets where demand charge management sophistication matters, enterprise AI-optimised platforms for large multi-depot franchise networks — maps software capability to operational need in a way that avoids both under-investment (inadequate capability producing suboptimal financial returns) and over-investment (enterprise platform capability that small fleets cannot utilise and cannot afford to maintain).
JD.com’s route-integration approach and SF Express’s departure-assurance-first philosophy represent two legitimate operational philosophies for fleet charging management — cost optimisation as the primary objective versus reliability assurance as the primary objective — that reflect genuine differences in logistics business model and customer proposition. For the logistics operators reading this guide and evaluating their own fleet charging management approach, understanding which of these philosophies best matches their own operational model is the starting point for evaluating which platform features matter most for their specific fleet.
China’s logistics sector electrification is not slowing. The fleet charging management software that operates these fleets is becoming as operationally critical as the TMS and WMS systems that have defined logistics IT for the past two decades. Getting it right — right platform, right features, right scale — is an operational investment decision that compounds in value with every vehicle added to the fleet.


